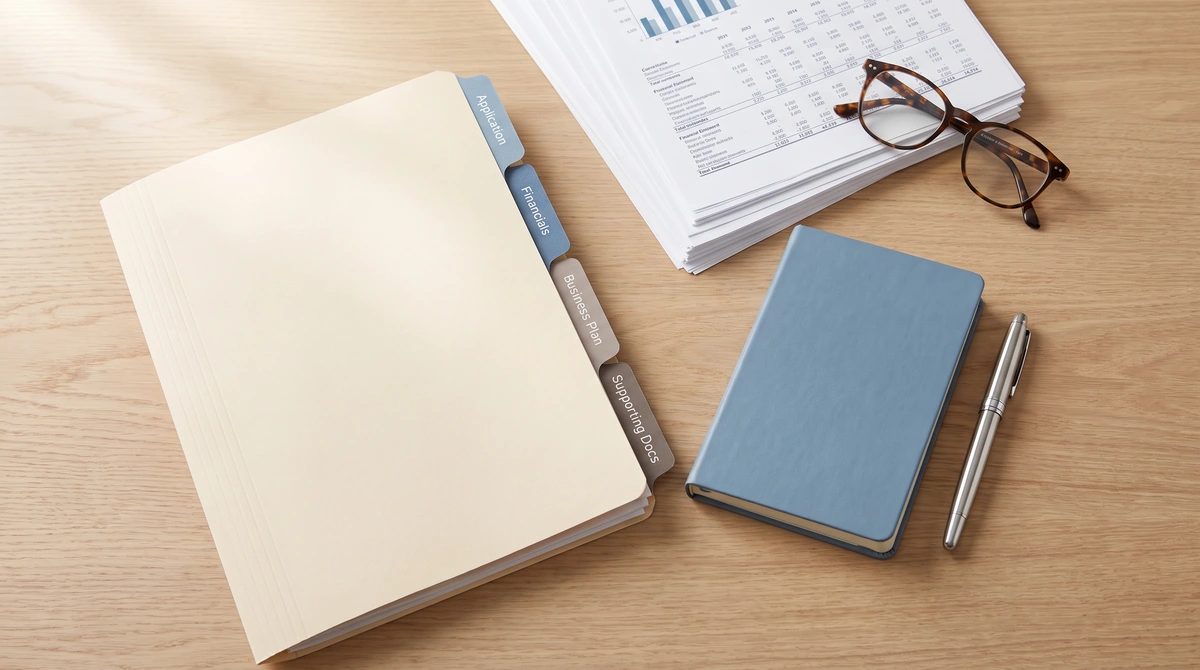
You are staring at three years of tax returns, a stack of bank statements, two half-finished projections, and an SBA form that keeps asking about “affiliates.” There is a person whose whole job is to turn that mess into a clean, lender-ready file — they are called an SBA loan packager.
The question is whether hiring one is worth the money for your specific situation. Some borrowers save weeks and improve their approval odds; others waste thousands on services they never needed.
This guide breaks down what a packager actually does, what they charge, when they earn their fee, when they don’t, and how to spot the ones who will take your deposit and disappear.
What Does an SBA Loan Packager Actually Do?
A packager is the person who assembles, organizes, and formats your complete SBA loan application package before it goes to a lender. Think of them as a project manager for your paperwork. They chase down documents, fill in forms, format your business plan, sanity-check your projections, and hand the lender a tidy, complete file — the goal being that underwriting has zero reason to send it back.
Packagers come in a few flavors. Some are employed by banks (often called Business Development Officers) and package deals for free as part of the lender’s service. Others are independent consultants who charge a flat fee or a small percentage of the loan.
It is important not to confuse a packager with a lender. A packager never makes the credit decision and never funds the loan — they only prepare the file. The lender still underwrites everything, and the SBA still has the final say on the guarantee.
What a Packager Prepares
A complete SBA loan package typically includes the following, all formatted, labeled, and tabbed:
- SBA Form 1919 (Borrower Information) and Form 413 (Personal Financial Statement)
- Form 912 (Statement of Personal History) where applicable
- Three years of personal and business tax returns, cleanly organized
- Business debt schedule with balances, rates, and monthly payments
- Business plan and one-page executive summary
- Three-year financial projections with cash flow modeling
- Use of proceeds narrative — how every dollar will be spent
- Collateral schedule and ownership/affiliate documentation
The lender receives one clean, complete package — not a shoebox of PDFs and text messages. That difference alone can shave weeks off the SBA loan application process.
How Much Does SBA Loan Packaging Cost?
Fees vary widely depending on who prepares your package and how complex your deal is. Here is what to expect:
| Packager Type | Typical Fee | How It’s Paid |
|---|---|---|
| Bank BDO (in-house) | $0 to borrower | Absorbed by the lender |
| Independent packager (small loan) | $1,500 – $3,500 flat | Half up front, half at submission or closing |
| Independent packager (larger 7(a) or acquisition) | $3,500 – $10,000 flat | Milestone-based; some paid at closing |
| Broker (packager + lender match) | 1% – 2.75% of loan amount | Typically at closing, from loan proceeds |
Key Fact: SBA Form 159
Anyone who is paid to help prepare your SBA loan package — including a packager, agent, or broker — must be disclosed on SBA Form 159, which is filed with the lender. Fees must also be considered “reasonable and customary” per SBA guidance. If a packager refuses to sign Form 159, walk away.
You should never pay a large upfront fee in exchange for “guaranteed approval.” No one — not a packager, not a broker, not even the lender — can guarantee an SBA loan before the file is underwritten.
When Hiring a Packager Makes Sense
Not every borrower needs to hire an outside SBA loan packager. Here is when the fee usually pays for itself — and when it doesn’t.
Good Reasons to Hire One
- Complex deal structure. Acquisitions with earn-outs, partner buyouts, multi-entity holdings, and stock-vs-asset purchases all require careful narrative and documentation. A packager who has seen these before can save you from a resubmission loop.
- You are time-poor. Running the business by day and building projections at midnight is a fast track to a sloppy file. If your time is worth more than the packaging fee, delegate.
- Weak or messy financials. If your books need cleanup or you have never produced projections, a packager (working with your CPA) will move the ball faster than a first-timer flying solo.
- You have no lender relationship. A packager who works with multiple SBA lenders often knows which one will actually fund your type of deal.
When You Probably Don’t Need One
- Simple working capital under $150K. Many lenders will walk you through the paperwork themselves.
- A strong existing lender relationship. Your banker already has your financials and will guide you through the SBA forms.
- Straightforward SBA Express requests. These are designed for speed and simpler documentation.
- Clean books and a proactive CPA. If your CPA can produce the financial exhibits, you can handle the SBA-specific narrative yourself.
Red Flags: Avoiding Packaging Scams
Watch Out
The SBA does not endorse, certify, or license loan packagers. Anyone marketing themselves as an “SBA-certified packager” or “SBA-approved packager” is misrepresenting their status. Real packagers describe their experience and references — not fake credentials.
Before you sign an engagement letter or wire any money, run through these vetting steps:
Ask for references from recent SBA borrowers
Request two or three clients whose loans closed in the last 12 months. A real packager will provide them.
Reject large upfront fees
A modest deposit ($500 – $2,500) is normal. Anything above that before a single document is prepared is a warning sign.
Confirm SBA Form 159 disclosure
Any legitimate packager will sign Form 159 disclosing their fee to the lender. Refusal is a hard stop.
Ignore anyone who “guarantees” approval
Approval depends on the lender’s underwriting and the SBA’s review. Guaranteed-approval promises are the calling card of predatory operators — the same pattern seen in many SBA loan scams.
DIY vs. Packager: A Quick Decision Framework
Most first-time borrowers overthink this decision. The honest answer is that it comes down to loan complexity, your time, and whether you already have expert help in your corner. If you are still on the fence, use this three-question test.
Key Takeaway
Answer three questions:
1. Is your loan over $500K or an acquisition? If yes, seriously consider a packager.
2. Can you dedicate 20 – 40 focused hours to assembling the file? If yes, DIY is realistic.
3. Do you already have a lender or CPA guiding you? If yes, DIY plus their help is often enough.
If you are on the DIY track and just need to find the right lender, the SBA offers Lender Match, a free tool that connects borrowers with SBA-approved lenders. Pair that with a solid application blueprint and you can absolutely package your own file.
The Bottom Line
A good SBA loan packager turns a paperwork nightmare into a lender-ready file, saves you weeks, and can genuinely improve your approval odds on complex deals. A bad one drains your bank account without adding value — or worse, damages your file with sloppy work. The difference is entirely about vetting.
Ask for references. Verify SBA Form 159 disclosure. Never pay for a “guaranteed” approval. And remember that many strong applications are packaged in-house by the borrower and their lender — no third party required.
Need Help Preparing Your SBA Loan Package?
Our team walks you through every form, projection, and financial statement — no upfront fees, no guessing. Get expert guidance from application to funding.